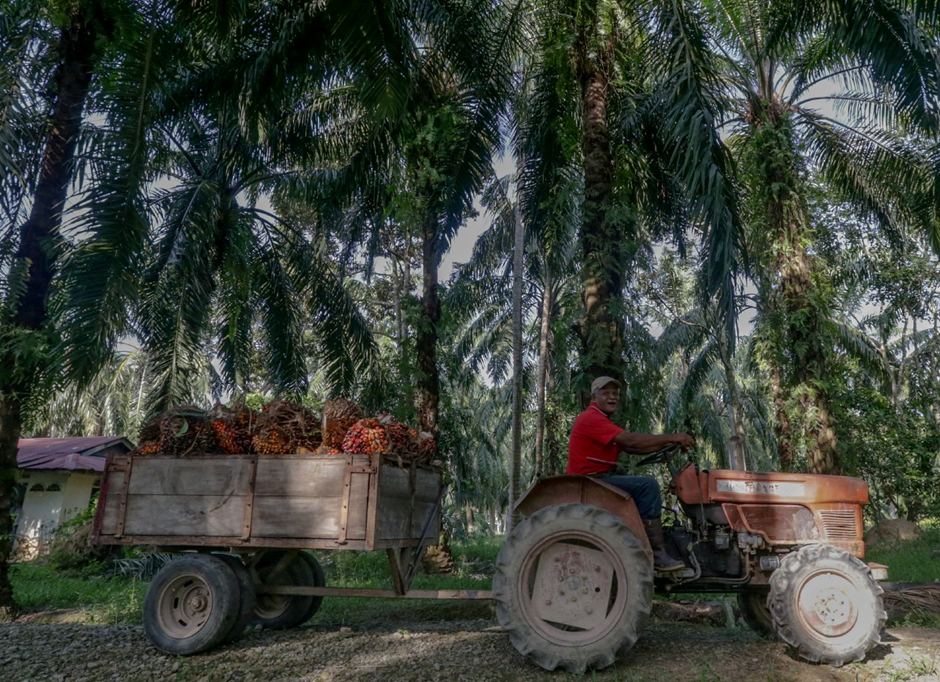
Hap Seng Plantations Favoured on Yield, Growth Potential

Hap Seng Plantations Bhd remains a preferred pick among Malaysian plantation stocks, supported by strong fresh fruit bunch (FFB) production growth, attractive dividend yields and an undemanding valuation.
CGS International Securities Malaysia Sdn Bhd maintained its "Add" call on the stock with an unchanged target price of RM3.35.
It noted that Hap Seng Plantations is trading at below 10 times its projected financial year 2026 (FY26) and FY27 price-to-earnings ratio, making it the cheapest stock under its Malaysian plantation coverage.
It said the plantation company is also expected to deliver dividend yields of more than six per cent over the next two years.
CGS International expects FY26 earnings to be supported by sector-leading FFB production growth and higher year-on-year crude palm oil (CPO) prices.
According to the firm, management has maintained its FY26 FFB production guidance of between 714,000 and 715,000 tonnes, representing growth of 16 to 17 per cent year-on-year.
The company's FFB output increased seven per cent in the first half of the year, accounting for 42 per cent of CGS International's full-year forecast.
The research firm is projecting a more conservative FY26 production growth of 13 per cent.
CGS International also highlighted Hap Seng Plantations' relatively lower cost pressures compared with industry peers, with the company securing its fertiliser requirements for 2026 in April and expecting fertiliser costs to increase by only five to 10 per cent year-on-year, compared with the 15 to 25 per cent rise anticipated for many plantation companies.
In addition, Hap Seng Platations may benefit from priority access to fertiliser supplies through its parent company, Hap Seng Consolidated Bhd, which operates a fertiliser trading business, it said.
Looking ahead, CGS International said the potential emergence of a strong El Niño weather pattern could weigh on FFB production in FY27 but may also boost palm oil prices.
For FY26, the firm forecasts the net profit to almost double to RM206 million from RM112.4 million in FY25 and stabilise to RM201 million in FY27, supported by higher production volumes and stronger palm oil prices.
Revenue is projected to increase to RM884.7 million in FY26 from RM702.4 million in FY25, before edging up to RM893.6 million in FY27.
The research firm identified stronger-than-expected dividend payouts and a sharp rise in CPO prices driven by El Niño-related supply concerns as potential catalysts for a re-rating of the stock.
However, higher production costs and weaker-than-expected sales volumes remain key risks.
Source: www.nst.com.my